Divest Oregon Responds to Treasurer Read's Net-Zero Plan

February 6, 2024

On February 6, 2024, Oregon Treasurer Read released "A Pathway To Net Zero: Positioning The Oregon Public Employees Retirement Fund For A Net Zero Carbon Future." The Divest Oregon response, provided to the Treasurer's office, is as follows:


"The Divest Oregon coalition welcomes the release of this net-zero plan. We appreciate Treasurer Tobias Read’s regular dialogue with our coalition of over 100 organizations who are dedicated to ensuring that our state pension fund invests in a sustainable future with solid returns. The Treasurer agrees with our coalition that the climate risks to PERS investments are real and require a substantial response to protect the pensions of more than 400,000 Oregonians. With the policies outlined in this plan, the Oregon State Treasury is taking an important step forward in considering these risks. But this is just the beginning: the success of this decarbonization effort requires Treasury's commitment to transparent reporting, a sense of urgency, and responsive policy-making as the effects of climate change on investment portfolios are increasingly understood. We look forward to our continued engagement with the current and incoming Treasurer, Treasury staff, and the Oregon Investment Council as they further define and implement these policies.”


What follows is the testimony presented by Divest Oregon representatives at the Oregon Investment Council meeting held on February 6:

  • Engagement & Transparency

    My name is Andrew Bogrand. I am the volunteer Communications Director for Divest Oregon. I would like to start by acknowledging the Oregon Investment Council and Chair Samples for allowing many hours of public testimony by Divest Oregon over the past several years on the risks of climate change on the Oregon State Treasury’s returns. I would also like to thank Treasurer Read and his Chief of Staff, Dmitri Palmeteer, for their positive engagement with us over the past several months. Our goal has always been for Treasury to address the financial risks of climate change and we are heartened that mitigating climate risk will now be Treasury policy. 


    Continuing to build trust through public engagement and transparency -- now and into the future – will be critical in ensuring that this net-zero plan succeeds.  


    Some will worry the policies laid out in this plan will go too far in the pursuit of “decarbonization” and jeopardize returns. Others will worry that the plan will fall short of reducing fossil fuel risk.


    Regardless of any one position, everyone will need to know how this plan is being implemented. In the short term, this means providing clarity on how this plan will be launched over the next year.


    In my professional career, I have worked on transparency reforms at home and abroad. We know that transparency is key to building mutual trust and confidence, including when it comes to addressing climate risks and moving us closer to net-zero emissions. Transparency is not just about providing information but tracking goals, progress, and impacts. It is about building public trust and confidence.  


    We urge you to consider how Treasury can build and maintain public trust in its net-zero commitment.  For one, the plan could use more clarity on how the OIC and the public will be kept up to date on progress and challenges. Information without engagement, or  “zombie transparency,” is always a challenge. This plan must be a living document grounded in regular, positive engagement with beneficiaries, stakeholders, and groups like Divest Oregon. 


    In implementing this plan, Treasury should look to the UN High-Level Expert Group on Net-Zero Emissions, which has published guidelines for net-zero plans that include:

    -- Establishing and publishing a timeline and deliverables for implementing the net-zero plan;  

    -- Describing the project team tasked with implementing the plan, including key roles and responsibilities; and,

    -- Creating a comprehensive annual reporting template to credibly demonstrate progress and identify barriers on the road to net zero.


    We look forward to our future engagement as an ever-broadening coalition with the Oregon Investment Council and the professional Treasury staff especially as this new net-zero plan is put in place.

  • True Net-Zero Needs to Be OIC Policy

    My name is Susan Palmiter. I speak on behalf of Divest Oregon, a coalition of over 100 organizations and over 1000 individual members. We commend the Treasurer for agreeing with us that climate change 1) poses a financial risk to our State’s pension fund and 2) creates a need to mitigate the negative impact it will have on beneficiaries’ returns. 


    This plan represents an important and significant policy shift for OPERF.  


    This shift for the Oregon Treasury and OPERF, which, as proposed, will need to be sustained through the next few decades by a climate-risk aware and evolving staff, many newly elected Treasurers, and newly appointed OIC members. And through those decades, which I and many people in this room may not live to see, unpredictable impacts of the unfolding climate crisis on financial markets will occur.  


    As the Treasurer’s plan acknowledges, the “pathway” that will optimally protect beneficiary returns from climate risk is unknown. If anything, the climate crisis is unfolding more quickly than scientists have expected, with faster warming, more severe weather events, and more rapidly approaching tipping points - all from which there is no return. At the same time, new pathways may appear so that OPERF can hit an 80% emission reduction by 2035 and Net Zero by 2040. Other public pension funds’ are moving to do just that. 


    Therefore, we urge the OIC to unequivocally embrace this overall shift as OIC investment policy. 


    Safeguarding the fund from climate risk should not be the job of a sole treasurer or the capable Treasury staff alone; it must be OIC investment policy to be credible and long lasting. Only a policy can guide work, provide oversight, and create accountability. The OIC has statutory responsibility - as ORS 293.731 states "shall formulate policies for the investment of OPERF and the acquisition, retention, management and disposition of investments." 


    Given the importance of this initiative, we ask that OIC members meet quarterly with the Treasury team responsible for implementing this work - similar to the quarterly asset class team oversight you are beginning. 


    We also ask that you request quarterly updates from the staff at OIC meetings - outlining the progress of the net-zero plan so we are all informed of any slow-downs or stalls. The urgency is real. The time for action is now.


    This Net Zero plan is inherently a policy. We urge the OIC to take an active role both in overseeing the implementation of the plan and how urgently the staff is acting to proactively protect beneficiaries. It needs to be an OIC policy. 


    Thank you for this opportunity to speak.


  • Financial Models Aren’t Keeping Up with Climate Change

    My name is Nancy Yuill and I am speaking on behalf of Divest Oregon.  I appreciate that the Oregon Treasury has developed this net zero plan.  It is a foundational document that has potential to evolve into effective policy to mitigate the financial risks to OPERF from climate change. 


    We all see climate change accelerating across Oregon and the planet.  The truth is: this Net Zero plan will only be effective if it has the ability to evolve and meet the rapidly deteriorating situation we are in and it is only as good as the financial models that are taking these changes into account.


    Foremost in your mind should be an understanding that current economic models used to model financial risk from climate change are not taking into account tipping points and cascades, nor the severe price adjustments that will reflect the climate risk.  Three professional articles in the past 7 months by economists and actuaries lay out the facts.  I am happy to provide copies of them at your request and I cite them in my written testimony.


    To summarize the findings,  standard economic models fail to consider domino effects of tipping points and feedback loops, which climate science tells us are not far away-and their risks are accelerating.


    To understand tipping points and feedback loops you need just imagine being on a road trip and having a hungry, tired child onboard; you know problems progress quickly and the tipping point to no return is unpredictable, and sooner than we hope. Then there is the domino effect, once one passenger in the car starts to melt down, you know more will follow in a cascading manner. That is the tipping point and feedback loop.


    Current economic models are also underestimating how quickly the planet is warming, and burning through our carbon budget.  And in the models, the measurement of costs from climate change damage exclude many of the risks anticipated to arise from climate change. 


    Ortec, who did economic modeling for Treasury in 2021 and 2022, thinks their model is underestimating financial damage because it is not accounting for tipping points or unprecedented changes in the climate system.


    Economists and actuaries are shouting to us that the impacts of climate change are much worse and happening much faster than financial models are predicting. 


     This net zero plan must evolve to incorporate updated economic models that best reflect the rapidly changing climate and the plan needs to keep looking for where you can accelerate the move towards net zero.  


    The 3 referenced articles are:

    -- The Emperor’s New Climate Scenario

    -- Loading the DICE against pension funds - Flawed economic thinking is putting your pension at risk

    -- Asleep at the Wheel-Risks of Climate Price Shocks

  • The Plan Must Evolve Quickly

    My name is Jenifer Schramm and I am representing Divest Oregon in this testimony.


    Divest Oregon will follow the implementation of the Treasurer’s plan in the months ahead, and encourage improvements. As Andrew discussed, we assume that the Treasury will create public trust in the plan by making plan progress accessible to all interested parties.


    An example of a necessary improvement to the plan is incorporation of all emissions data. Currently, the plan does not require reporting on greenhouse gas pollution resulting from the use of OPERF’s fossil fuel investments – scope 3 emissions. Instead, the baseline measures only emissions from the production of those fuels – scope 1 and scope 2 emissions.  This unmeasured and unreported scope 3 pollution has a huge impact on the climate and a huge impact on the risk to OPERF investments. Again, this plan currently only measures pollution from the production of fossil fuels, not the actual and intended use of the fuels. 


    This is like measuring cancer risk from cigarettes by measuring cancer risk from growing tobacco and operating cigarette factories,  while totally ignoring the cancer risk caused by actually smoking the cigarettes produced by those investments.​ Treasurer Read’s plan on page 40 notes that “As the standards and reporting improve around Scope 3, Treasury will look to incorporate that data into our decision making.” Some corporate reporting of Scope 3 emissions, including reporting for Big Oil, is available now. Why not use it?  


    This is just one example of the need for ongoing updates of the plan. You can be sure  that as the Treasury and the Oregon Investment Council inform the public how the plan and the implementing policy evolve on key issues, the Divest Oregon coalition will keep an open door and continue to look for updates and improvements.

  • Climate Urgency

    My name is Gary Wallmark. My wife Linda and I are retired PERS members from Eugene. I’m a volunteer for Divest Oregon concerned about the stability of our retirement system as the climate continues to change.


    I thank the Treasurer for presenting his Net-Zero investment plan and the Oregon Investment Council for considering how Oregon can best transition toward greener, safer investments. I’m glad this proposal is being made now rather than after the next Treasurer comes into office. It’s a blueprint we can start building upon now.


    Some might think, “We’ve got this covered—nothing more to do.” That would be a mistake.


    My wife and I spent the last 50 years hiking throughout the west. We heard a little about the prospect of climate change years ago but it seemed VERY distant — it “wouldn’t be a problem for generations”. Then we started seeing things change — sometimes slowly, sometimes fast.


    We planned a trip to Mt Rainier in the 80s to hike in the glacial ice cave, but the week before we left the cave was closed —  car size ice chunks were falling from the ceiling. SURPRISE. As we returned to the park over the years, we saw that the huge Nisqually glacier kept receding up the mountain. It became difficult to see glaciers in Glacier National Park. SURPRISE. 


    River levels were dropping. Rafting on the Colorado, we encountered a rapid that shocked our experienced guide — it hadn’t been there in more than a generation and wasn’t there just days before. SURPRISE. 

    And large expanses of forest, in Oregon and throughout the west, were sick and dying. More wildfires, more smoke, more closed roads, more charred land, more burned communities. SURPRISE, SHOCK, LOSS, and GRIEF.


    The predictions were wrong - the earth is heating faster than expected. We feel and see it. Things that were supposed to happen “IN THE FUTURE” are happening NOW. Change is non-linear — chaotic with sudden, unanticipated consequences. SURPRISE. This is no longer a problem only for remote future generations. It is OUR problem and will become an even bigger problem for our children and grandchildren. No wonder the state has adopted policies to reduce greenhouse gas emissions. 


    These accelerating disruptions are sapping our state retirement savings. The S&P 500 fossil fuel energy sector is worth barely more today than it was 10 years ago. Investments that once seemed sound may become costly stranded assets. SURPRISE—and OUCH. We don’t want our portfolio to be filled with “buggy whip” investments.


    We would like the Treasury to divest NOW from fossil fuels, as the New York pension fund has done. But we are glad Treasurer Read has taken this first step. We, and other PERS members and retirees, will watch how quickly Treasury implements the plan, and watch how the next Treasurer builds on it to protect our PERS investments. 


    Far-sighted leadership will be required to avoid more SURPRISING OUCHES. 


September 25, 2026
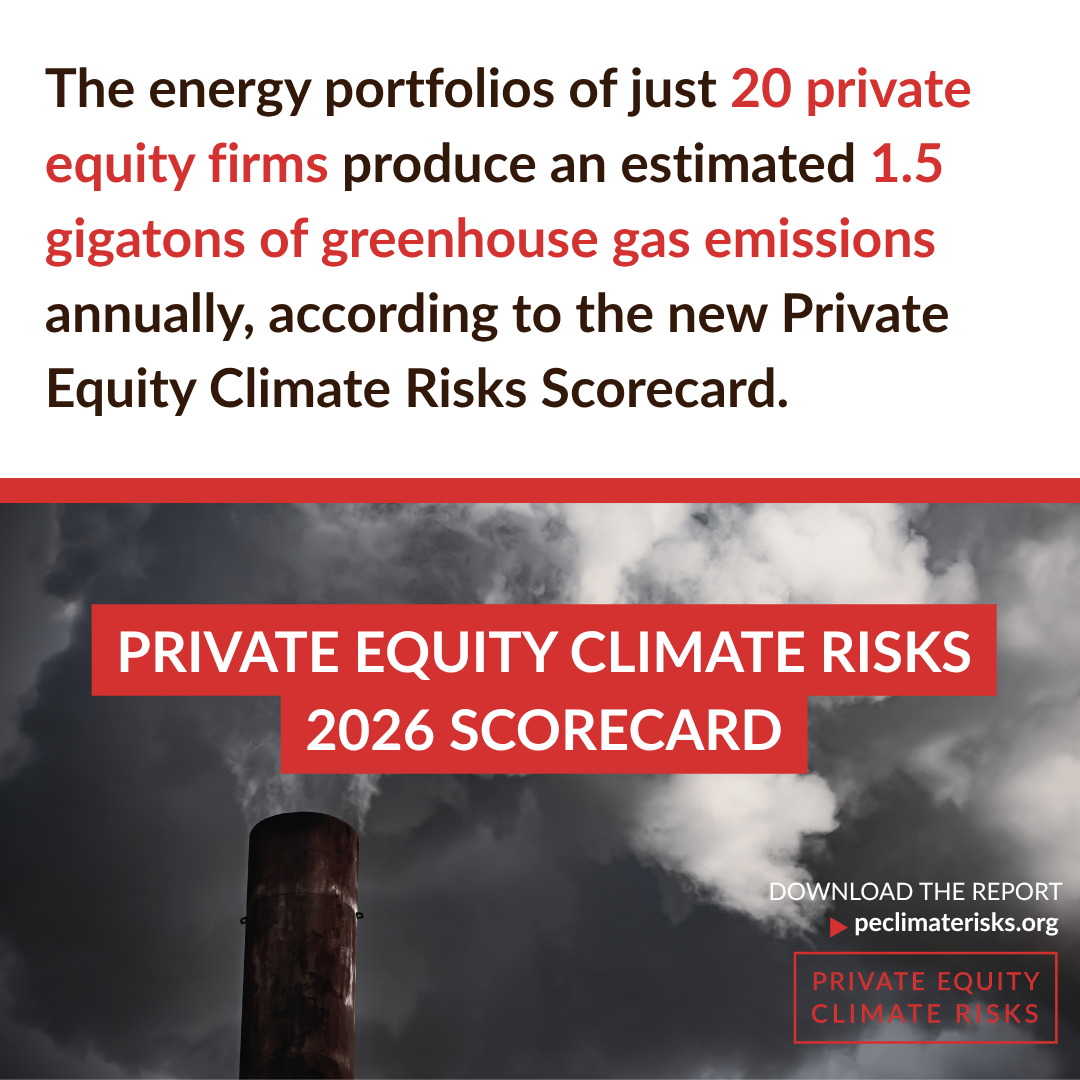
Global emissions are up. Private equity is a culprit – and so is the Oregon Treasury. Private Equity Climate Risks consortium has just published its latest scorecard and report , endorsed by 21 organizations working on climate, environmental justice, financial accountability, and consumer issues, documenting (pages 10-28) that: ⚠️ 20 private equity firms’ energy portfolios: are responsible for producing an estimated 1.5 gigatons of greenhouse gas emissions annually. include more than 1,000 assets: 244 energy companies 250 oil and gas fields 15,000 miles of pipelines 35 LNG terminals 13 coal terminals dozens of LNG tankers hundreds of fossil fuel power plants. The Guardian (9/15/2026) on the Private Equity Climate Risks report: World’s top 20 private equity firms produce more greenhouse gases a year than most countries, report finds : Firms manage $7.3tn in assets and could afford to transition away from fossil fuels yet invest in natural gas and coal-fired plants to power datacenters. “Private equity firms have emerged as the largest datacenter owners outside  of big tech.” (See the case study on data centers starting on p 25 of the report.) What about Oregon? ⚠️Six private funds, held by the Oregon Treasury, hold at least 473 fossil fuel assets. These firms are: Blackstone, Brookfield Asset Management, Encap Investments, EQT, Global Infrastructure Partners (GIP), Quantum Capital. All are in the Real Assets holdings. As Private Equity Stakeholder Project commented to the Oregon Investment Council (see Public Comment book of 9/2/2026 , page 8): Through existing OST fund commitments, OPERF likely has exposure to many of these 473 fossil fuel assets, which also create global climate risk. Some funds held by OST are making new investments in fossil fuels, pushing the pension fund further from Oregon’s Climate Resilience Investment Act (CRIA) goals and creating more risk for the fund. One example: BlackRock’s GIP. Oregon invested in GIP (Global Investment Partners fund), created to finance a new LNG terminal (see Is the Oregon State Treasury Supporting Environmental Racism in the Gulf South? Divest Oregon 9/26/2024). The fund is now managed by BlackRock and it plans to acquire AES, a massive US-based utility company that also backs 23 fossil fuel-fired power plants globally. If the AES deal closes, BlackRock’s GIP will nearly double its fossil fuel power plant portfolio to 50, spanning 11 countries.
August 6, 2026
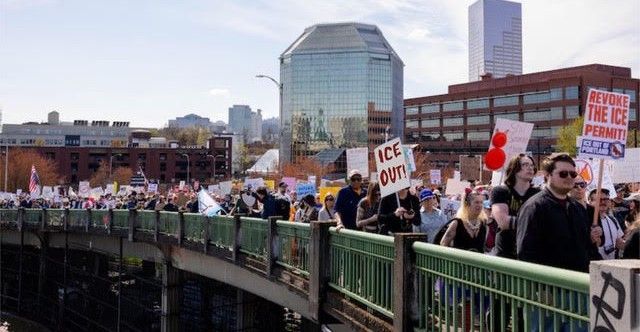
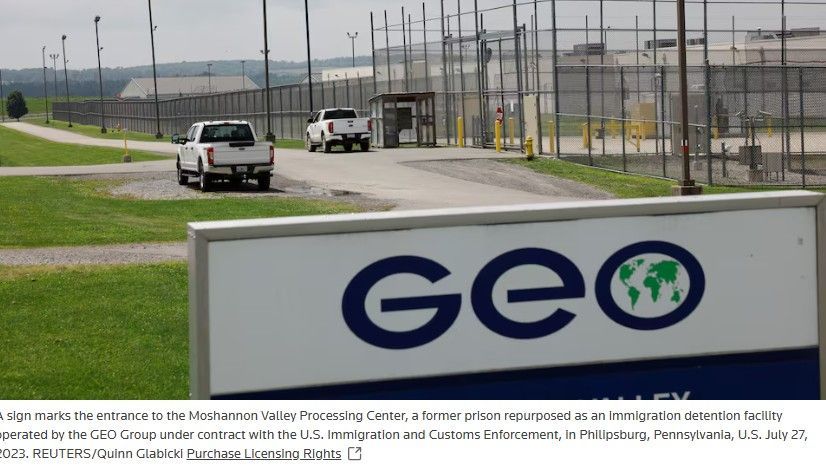
“As a PERS beneficiary, I am horrified that my pension funds private prison contractors and ICE detention centers.” Three recent Letters to the Editor of The Oregonian voice deep disquiet that the Treasury invests in immigrant detention facilities and spyware that are internationally recognized as engaging in human rights abuses and are flagrantly violating constitutional rights – instead of constructive investments. In June 2025, Oregon Treasury data shows investment of $51 million in CoreCivic and Geo Group, private prison contractors, and Palantir, maker of surveillance software used by ICE against US residents. Divest Oregon has been asking the Treasurer for years : Why aren’t investments screened to comply with Oregon Investment Council standards? See the blog: Why is the Treasury still investing workers’ retirement in fossil fuels, ICE contractors, and surveillance technology? for the backstory. In May, Treasurer Steiner stated that Treasury used its shareholder power to vote against four candidates for Geo Group’s board of directors because it was not conforming to Treasury’s investment standards – but kept the stock: Treasurer Steiner is “ deeply troubled ” about ICE contractor Geo Group…but OST has been a shareholder for years. The Treasury is investing public employee money. It has a responsibility to the beneficiaries and to all of us to follow its own investment guidelines. The letters voice a strong call for change: PERS should divest from ICE-contract prisons ( PDF , The Oregonian 7/27/2026) “Human Rights Watch reports that 52 people died in the custody of U.S. Immigration and Customs Enforcement in the first 500 days of President Donald Trump’s second term…." “It is tempting to feel powerless about this senseless waste of life. But here in Oregon, we have an opportunity to make a difference. We can demand that the Oregon Public Employees Retirement System divest from The Geo Group and Core Civic, two of the largest for-profit private prison corporations, which contract with ICE to run immigration detention facilities.” Oregon shouldn’t invest in ICE prisons ( PDF , The Oregonian 7/31/2026) “As a PERS member, I am not comfortable profiting from other people’s misery, and I am confident that others feel the same." “Reduced public investments and increased public awareness could even make investments in Geo Group and CORE Civic less attractive. Oregon should lead opponents of the cruelty in this immigration crackdown, epitomized by these prisons." Divest PERS from ICE-contract prisons ( PDF , The Oregonian 8/3/2026) “As a PERS beneficiary, I am horrified that my pension funds private prison contractors and ICE detention centers." “Oregon State Treasurer Elizabeth Steiner said she was 'deeply troubled' by Geo Group’s practices, and that the Treasury had used its shareholder power to vote against four candidates for the company’s board. Has that vote had any noticeable effect? Will Geo Group change its business practices as a result? These companies might take notice if the Oregon Treasury began pulling its investments.” “Like the people of Minneapolis, Oregon Gov. Tina Kotek, Oregon Attorney General Dan Rayfield and Portland Mayor Keith Wilson stood up to ICE. This is the moment for our Treasury staff to show the same courage."
July 6, 2026
Photo by SpaceX on Unsplash In a July 1 article Reuters reported that Oregon Treasurer Steiner wanted guidance from the federal Securities and Exchange Commission (SEC) about SpaceX. How should pension funds handle the new company with the giant market valuation? SEC Commissioner Mark Uyeda answered Elizabeth Steiner in an interview in Reuters . One takeaway is his simple point that if you don't like the governance arrangements of a stock, don't buy it. A message from the SEC's Uyeda: If you don't like SpaceX's governance, don't buy the shares ( Reuters Sustainable Finance , July 1, 2026) Note: The Oregon State Treasury has $6.8 million in exposure to SpaceX through one public equity index fund and one global equity portfolio ( Portland Business Journal July 2, 2026). Divest Oregon has made the same point to Treasurer Steiner, repeatedly. For example, Treasurer Steiner posted on Facebook on May 6, 2026 that she is “deeply troubled” by the ways ICE contractor Geo Group fails to adhere to Oregon Investment Council (OIC) policy. Divest Oregon responded : The Oregon Treasury has held stock in private prison/immigrant detention contractors for years, in spite of well-publicized abuse. If a company is violating OIC policy the Treasury has an obligation to sell the stock. In fact, Treasury’s screening process can and should prevent purchasing or holding stock that violates OIC/Treasury standards. The SEC Commissioner quoted in the Reuters ’ interview about SpaceX also says pension funds have the duty and ability to do such screening: Question by Reuters to SEC Commissioner Uyeda: "You write that ‘If prospective investors have concerns with the governance arrangements, then their most powerful tool is to not purchase shares of the stock.’ But critics like some big pension funds say the fast-track addition of SpaceX to big indexes could make them unwilling buyers of the stock. What would you say to such critics? Response from SEC Commissioner Uyeda: "Large pension funds have choices with respect to ​their investment decisions as part of their fiduciary duty to the plan. While index funds may have certain conveniences and low costs, there is a trade-off to outsourcing securities selection to a third party. There are alternatives, such as selecting a fund that follows a different index or is actively managed, or engaging in customized direct indexing that would provide more control over the portfolio.”
May 19, 2026
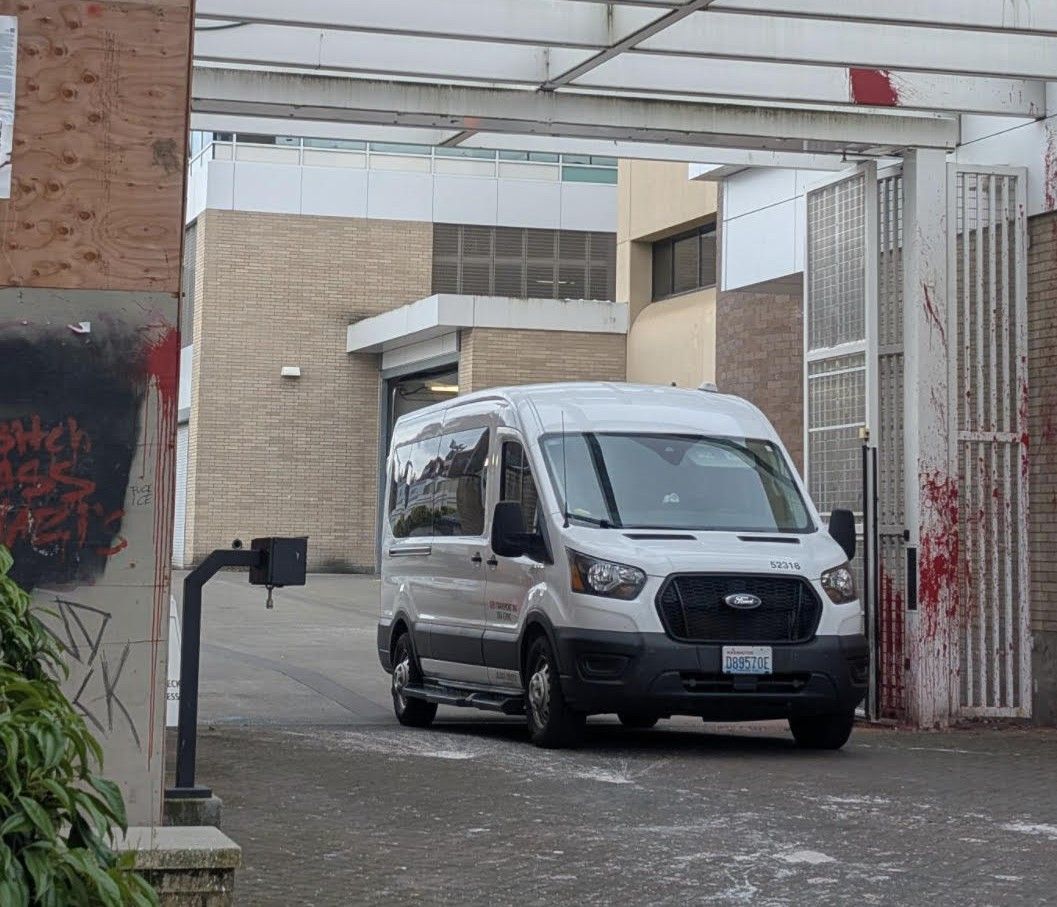
A Geo Group van leaving the Northwest ICE Processing Center in Portland Oregon. May 2026
April 9, 2026
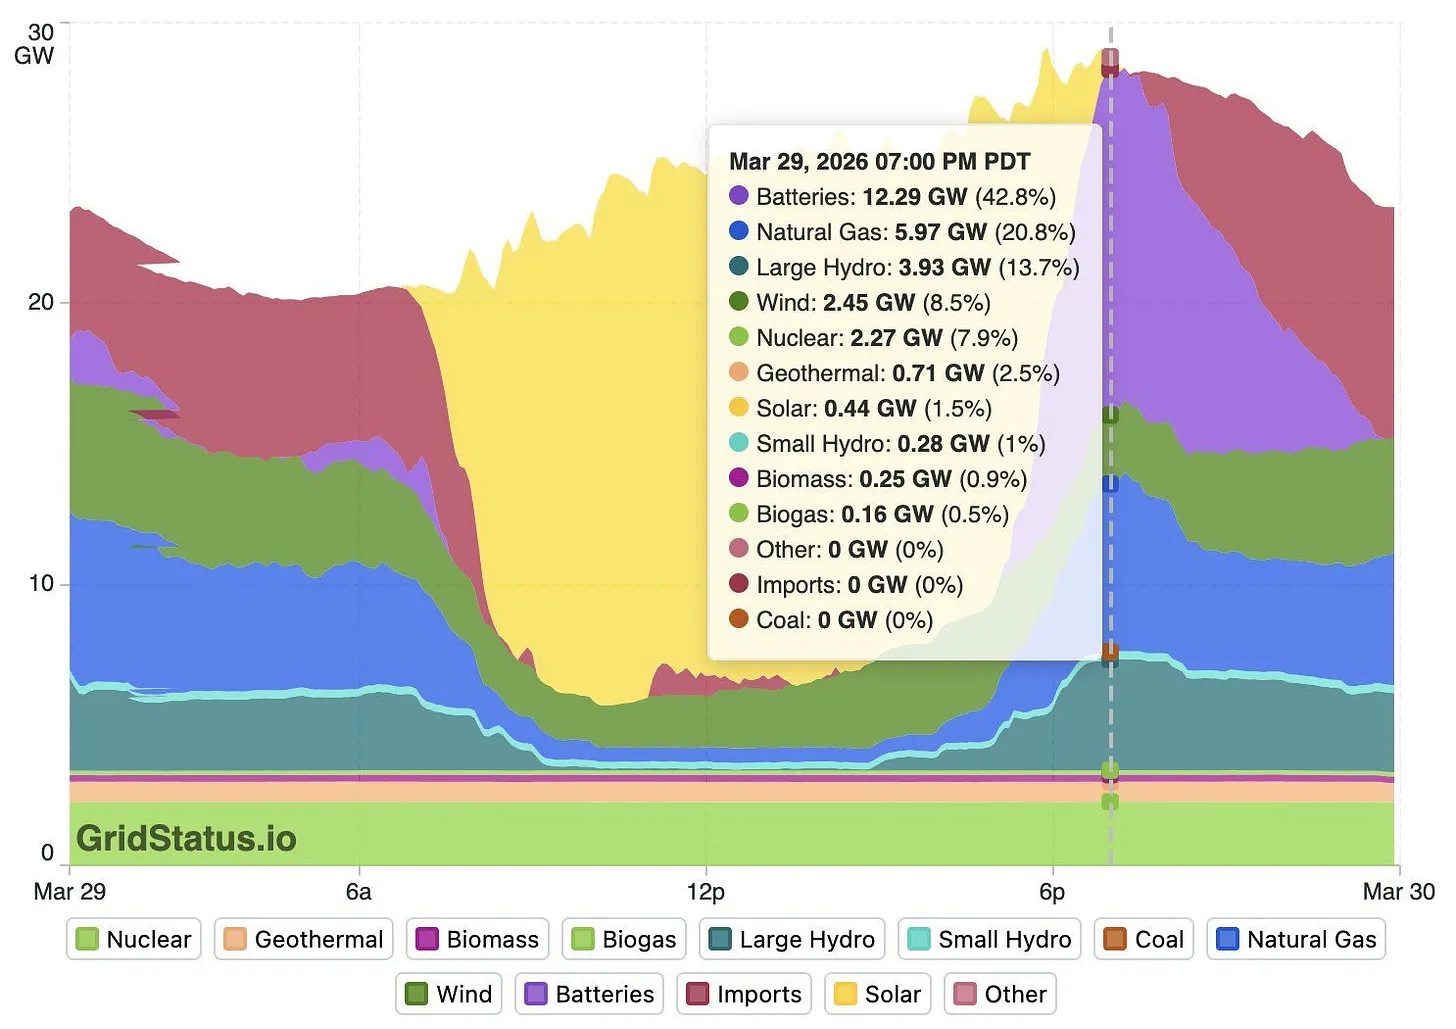
At the March 2026 OIC meeting, John Goldstein from Goldman Sachs spoke of the strength of renewable energy stocks (recap in Net Zero Investor 5/3/2026 ). Bill McKibben shows us how the sector is evolving with battery technology advances. Night into Day ( The Crucial Years substack 3/30/2026): “For the first time, the United States now has the capacity to supply 100% of domestic energy storage project demand with American-built systems,” said Noah Roberts, executive director of the U.S. Energy Storage Coalition. “That is a fundamental shift from where we were just a year and a half ago, when the majority of battery storage systems were imported.” “Already, the U.S. has enough capacity to meet demand for finished grid battery enclosures…. By the end of this year, the U.S. will also achieve self-sufficiency in a higher-value part of the supply chain: the battery cells themselves. It’s a major industrial coup that is bringing thousands of high-tech manufacturing jobs to communities across the country.” Solid-state batteries are becoming a possibility; they promise to solve several problems: “Batteries are now being tested by multiple companies that can go 800 miles on a single charge….“In September, Mercedes drove a modified EQS over 1,200 km (745 miles) using 106 Ah solid-state battery cells supplied by US-based Factorial Energy. Factorial launched the first commercial solid-state battery program in the US …earlier this year.” The Finnish company Donut Labs shows where this is heading: “The Donut batt can charge to full in five minutes…; has a practically unlimited lifespan (100,000 charging cycles); is unaffected by heat and cold (-30C to 100C); and contains no rare earth, precious metals or flammable liquid electrolytes. With all that, Donut Lab says it will be cheaper to produce than conventional lithium-ion batteries…” “And the technological miracles are only beginning. For instance, Christopher Mims reported last week in the Journal on a new round of ‘thermal batteries that store solar power as heat instead of electricity, perfect for use in high-temperature industrial processes.’” “Marija Maisch was reporting in January that…salt-based batteries are nearing price and performance parity, if not for cars then for utility scale batteries.” And this chart shows the surge of batteries coming online as solar installations lose sunlight. Night into day.
March 17, 2026
A question from Divest Oregon, a coalition of a hundred organizations with strong PERS representation, remains unanswered: What screening process does the Oregon State Treasury (OST) use, if any, when investing PERS funds or choosing investment managers? Is the Treasury screening investments in fossil fuel companies? Andrew Bogrand, Divest Oregon’s Communications Director, spoke at the Oregon Investment Council (OIC) in January 2026. He noted that investment in fossil fuels contributes to global instability, using Venezuela as an example. (See this blog .) The current Iran war emphasizes this point. Andrew regularly comments on the ties between insecurity and fossil fuels as a policy lead for human rights and natural resource justice at Oxfam. The argument that fossil fuel investments are a sensible diversification of a portfolio has long been outdated. But looking at the most recently published June 2025 public equity and fixed income data, the Treasury is still investing in fossil fuels. Under fiduciary duty and the Climate Resilience Investment Act ( CRIA ), the Treasury must move to alternative investments that align with the reality of climate change and a rapidly destabilizing world. Is the Treasury screening investments prone to legal liability, human rights abuses, or reputational risk? In an April 2023 report , Divest Oregon called out the Treasury's investment in private prisons and surveillance technology as context for the question: Does the Treasury have a screening process? If so, what is the screening process? One example given in that report was the NSO/spyware technology that OST heavily invested in. The Guardian reported extensively (2022) on the OST’s investment in NSO/Pegasus spyware: “However, it now appears that the Oregon pension fund, one of the most prominent in the US, gave its tacit approval over an investment in NSO several years ago – at a time when security researchers were already publicly raising alarms about the company.” In a more recent report, Oregon Treasury’s Investment Screening Failures ( October 2025 ), Divest Oregon again questioned the Treasury’s investment screening process. Examples of questionable investments included GEO Group, CoreCivic, and Palantir. Investments in GEO Group and CoreCivic fund private prison contractors and ICE detention centers. Investment in Palantir funds ICE surveillance software used against US residents. See additional information below for each of these companies. The most recent public data ( June 2025 ) shows that the Treasury continues to invest in these private prison and surveillance technology companies with a long history of human rights abuses and legal vulnerability. These companies are central to the current federal administration’s construction of a police state and its massive violation of due process. See Trump’s Mass Deportation Campaign ( The New Yorker 3/15/2026). For example: Recent private prison contractor GEO Group news: In February 2026, the Supreme Court found that GEO Group, a private prison operator running an Immigration and Customs Enforcement (ICE) facility, cannot claim governmental immunity from lawsuits for violating human trafficking laws, even if those violations were under government orders. Recent surveillance technology company Palantir news: In Portland, now, Palantir’s Elite app is being used to identify potential deportation targets, generate dossiers on individuals and provide a “confidence score” on the person’s address. ( The Guardian 3/13/2026) Why should the Treasury screen its investments? Screening is necessary to avoid investments that contravene Treasury standards, OIC policy, legal standards including fiduciary duty, or Oregon State law. For instance: The Oregon Department of Justice has recently opened an inquiry as to whether OST investment in companies with contractual ties to ICE violates the Oregon Sanctuary Promise Act of 2021 . The CRIA Act of 2025 mandates that the Treasury: -- “actively analyze and manage” climate risk to the portfolio -- report on its progress toward investing in public equity holdings that incorporate the tenets of a just transition in their overall priorities and portfolio
February 18, 2026
Part 2: Building on Oregon State Treasury’s 2025 Progress toward Net Zero Emissions Divest Oregon applauds initial action, offers recommendations for future reporting, including the use of multiple metrics
February 18, 2026
Part 1: Building on Oregon State Treasury’s 2025 Progress toward Net Zero Emissions Divest Oregon applauds initial action, offers recommendations for future reporting, including the use of multiple metrics
January 29, 2026
Thanks to the passage of CRIA and the Coal Act, Oregon is moving toward a more transparent assessment of climate-related risks, engaging with asset managers and companies, and identifying climate-positive investments. OPERF has nearly $90 million invested with Exxon, $40 million in Chevron, and $5 million in Shell. Can the Treasury hold these companies accountable and protect the wider portfolio from major conflict exposure? Following is incisive testimony to the January 2026 Oregon Investment Council by Andrew Bogrand, Divest Oregon’s volunteer Communications Director. For over five years, the Divest Oregon coalition has encouraged the Oregon State Treasury to take seriously the financial risks associated with fossil fuel investments, particularly within the context of the wider energy transition. Treasury, as well as the Oregon Investment Council, has listened and responded. Thanks to the 2025 Climate Resilient Investment Act (CRIA) and the 2024 Clean Oregon Asset Legislation (COAL) Act , our state is moving toward a more transparent assessment of climate-related risks, engaging with asset managers and companies, and identifying climate-positive investments. Of course, much of the work remains. In the spring of 2025, Divest Oregon provided testimony to lawmakers in Salem about the coalition’s support of CRIA. We shared how the bill would help Treasury address “new economic realities, where geopolitical contestation…and natural resource competition will upend the financial logic of passive investing.” A year later, this statement rings painfully true. We stand on the precipice of resource-driven conflicts in Venezuela, Greenland, and Iran. We are witnessing a deterioration of the international rules-based order, which will come with serious financial implications. This breakdown is not random. Chevron has played “the long game” in Venezuela, spending millions lobbying the Trump administration and positioning itself to profit following the US invasion. Shell is seeking a multi-billion gas project following the illegal ouster of President Maduro, which presumably also secured ExxonMobil’s interests – not in Venezuela, but in neighboring Guyana . And, the American Petroleum Institute, an industry lobby group including Chevron, Shell, and Exxon, recently pledged to “stabilize Iran” if the regime is ousted there, too.  Of course, whether these companies will profit from this new era of resource colonialism remains unclear. Darren Woods, the CEO of ExxonMobil, said bluntly that Venezuela is “un-investable.” Chevron has also acknowledged that any future work in Venezuela will require extensive guarantees and long-term stability, conditions which remain absent. Despite all the money spent on lobbying, the oil market remains volatile and these companies will likely seek taxpayer support and sanctions relief for risky bets abroad Treasury has nearly $90 million invested with Exxon, nearly $40 million in Chevron, and over $5 million in Shell. Now the question is how to hold these companies accountable and protect the wider portfolio from major conflict exposure. Not all energy companies are equal. In contrast to Chevron, France’s TotalEnergies, which Treasury also owns, has no intention to enter Venezuela despite its operations in nearby Suriname, presumably worried that their presence could make a humanitarian crisis worse or even directly fund human rights violations. If Treasury is serious about engagement, as set forth in CRIA, now is the time to exercise this commitment toward the most politically-exposed companies. Extraction by military force pushes the absolute boundaries of the social license to operate and undermines other holdings in Treasury’s portfolio. Companies have a major and well-recognized responsibility to avoid contributing to war. This responsibility is rooted in the UN Guiding Principles on Business and Human Rights as well as in international humanitarian law. Companies are expected to conduct rigorous human rights due diligence to ensure that their operations, supply chains, and technology do not fuel or contribute to conflict. If companies like Chevron and Exxon fail to respond to engagement along these lines then divestment is both an appropriate business decision -- and the right thing to do.