The Urgency of Now to Shift to Renewables

June 18, 2024

These articles were shared with the members of the Oregon Investment Council in June 2024.


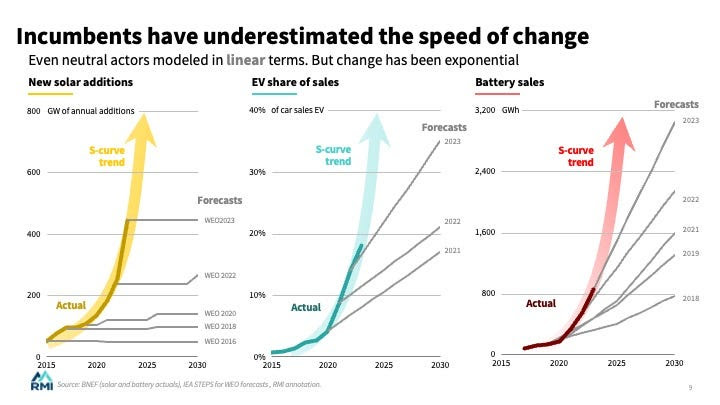
When considering the speed of the transition, here are some important data points:


“The E.V. market has hit an inflection point,” said Randy Parker, chief executive of Hyundai Motor America, which will begin producing electric vehicles at a factory in Georgia by the end of the year. “The early adopters have come. They’ve got their cars. Now you’re starting to see us transition to a mass market.”


The world has moved on to the steep part of the S curve (as shown below), which will sweep us from minimal reliance on renewable energy to minimal dependence on fossil fuel. Last year or this year, we will hit peak fossil fuel demand — the advent of cheap solar and wind and batteries, combined with rapidly developing technologies like heat pumps and EVs, has finally caught up with the surging human demand for energy even as more Asian economies enter periods of rapid growth. (comments by Bill McKibben)

When considering the risk of not taking firm action regarding climate risk to the portfolio, this recent Forbes article may be of interest:


Note that the risk calculated by Ortec recently for the Government of Singapore (GIC) is even higher than the risk calculated back by Ortec in 2021/2022 for OPERF. 


The author states: “There is another type of risk that cannot be prudently minimized through diversification, however, called “systemic” or “systematic” risk. Systemic risk causes assets to decline in value together; diversification is of no help. The investing world was jarred into recognition of systemic risk by the Global Financial Crisis of 2007-2009, when broad markets declined in sync (the peak-to-trough decline in the S&P 500, for example, was 57%). That particular systemic risk was unforeseen by most investors, but presently there are a number of systemic risks that we can identify and even expect, that will have severe implications for retirement accounts and funds. One of these is climate change.. 


These data have obvious implications for pension fund trustees’ fiduciary duty to protect trust property. Fiduciaries can protect their funds from transition risks by changing their investment mix to reflect changing energy practices and policies.  But they cannot protect the trust from systemic climate-caused physical damage by diversification. Their only option is to take all reasonable actions to do what they can, jointly with other institutional investors, to engage and support company practices and governmental policies that will abate climate change.
October 13, 2026
When Will the Oregon Treasury Comply with the COAL Act? Divest Oregon’s COAL Act passed in 2024. The statute mandates annual reporting by the Oregon State Treasury (OST) to the Legislature “on actions taken pursuant to the act.” The COAL Act spells out that OST can only remain in a thermal coal investment if the company is transitioning to clean energy on a reasonable timeline. A full report under the COAL Act would document where each coal company is in its transition process, when OST expects it to be completed, and actions that will be taken if the transition is not occurring. The Treasury’s 2025 Net Zero Plan Progress Report does not comply with the statute. Table 5, shown below, was presented with this text: Staff determined that as of November 30, 2025, the portfolio had $15 million worth of investments in 12 securities identified as “Thermal Coal” companies, a decrease from $28,979,710.04 worth of investments in 21 securities reported by staff in 2024. p. 26 Divest Oregon promptly pointed out (p. 16) the contrast between the report and the statute.
September 25, 2026
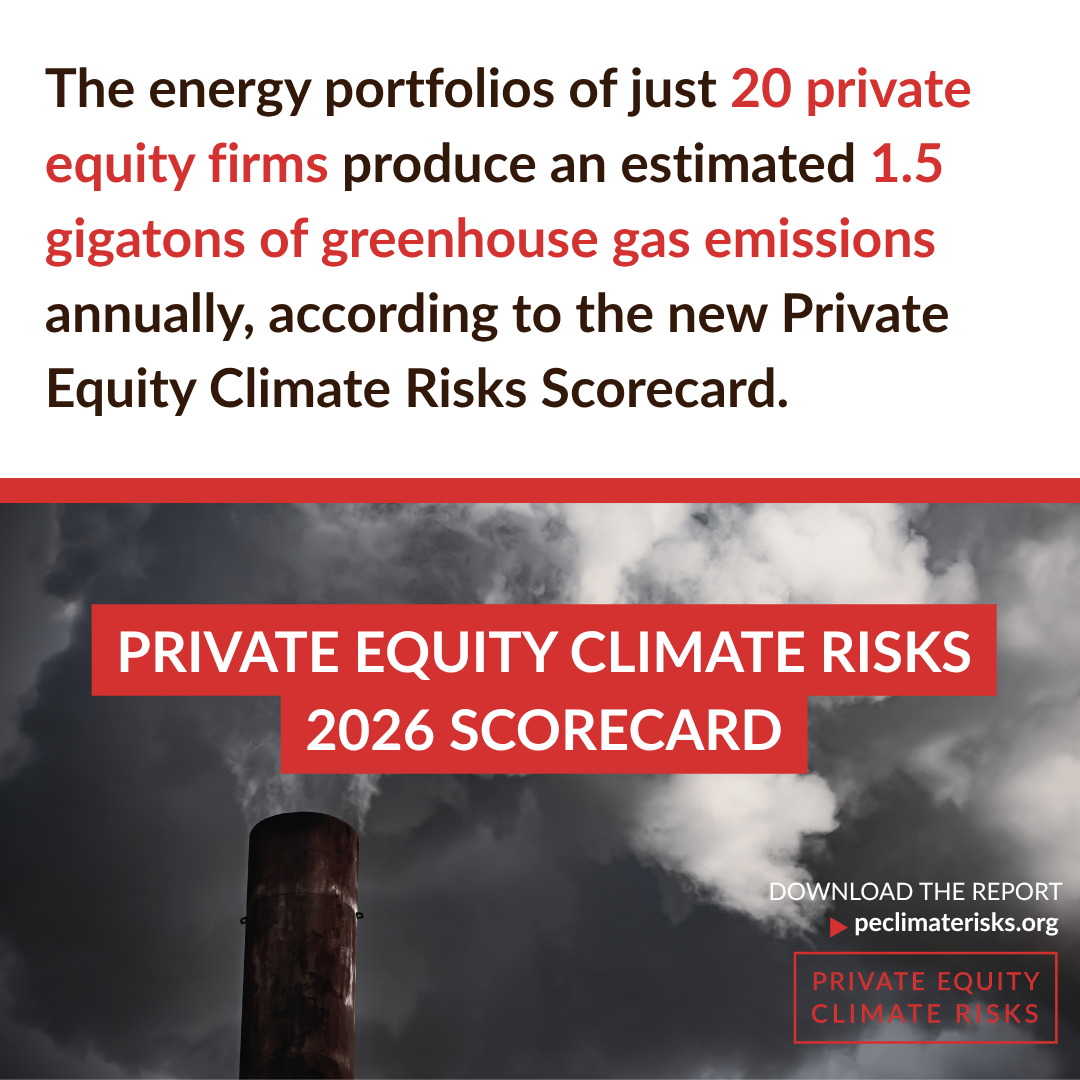
Global emissions are up. Private equity is a culprit – and so is the Oregon Treasury. Private Equity Climate Risks consortium has just published its latest scorecard and report , endorsed by 21 organizations working on climate, environmental justice, financial accountability, and consumer issues, documenting (pages 10-28) that: ⚠️ 20 private equity firms’ energy portfolios: are responsible for producing an estimated 1.5 gigatons of greenhouse gas emissions annually. include more than 1,000 assets: 244 energy companies 250 oil and gas fields 15,000 miles of pipelines 35 LNG terminals 13 coal terminals dozens of LNG tankers hundreds of fossil fuel power plants. The Guardian (9/15/2026) on the Private Equity Climate Risks report: World’s top 20 private equity firms produce more greenhouse gases a year than most countries, report finds : Firms manage $7.3tn in assets and could afford to transition away from fossil fuels yet invest in natural gas and coal-fired plants to power datacenters. “Private equity firms have emerged as the largest datacenter owners outside  of big tech.” (See the case study on data centers starting on p 25 of the report.) What about Oregon? ⚠️Six private funds, held by the Oregon Treasury, hold at least 473 fossil fuel assets. These firms are: Blackstone, Brookfield Asset Management, Encap Investments, EQT, Global Infrastructure Partners (GIP), Quantum Capital. All are in the Real Assets holdings. As Private Equity Stakeholder Project commented to the Oregon Investment Council (see Public Comment book of 9/2/2026 , page 8): Through existing OST fund commitments, OPERF likely has exposure to many of these 473 fossil fuel assets, which also create global climate risk. Some funds held by OST are making new investments in fossil fuels, pushing the pension fund further from Oregon’s Climate Resilience Investment Act (CRIA) goals and creating more risk for the fund. One example: BlackRock’s GIP. Oregon invested in GIP (Global Investment Partners fund), created to finance a new LNG terminal (see Is the Oregon State Treasury Supporting Environmental Racism in the Gulf South? Divest Oregon 9/26/2024). The fund is now managed by BlackRock and it plans to acquire AES, a massive US-based utility company that also backs 23 fossil fuel-fired power plants globally. If the AES deal closes, BlackRock’s GIP will nearly double its fossil fuel power plant portfolio to 50, spanning 11 countries.
August 6, 2026
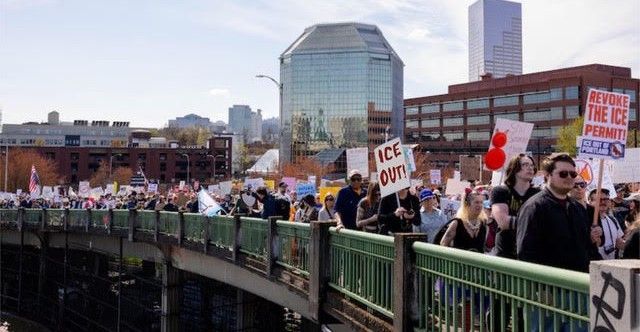
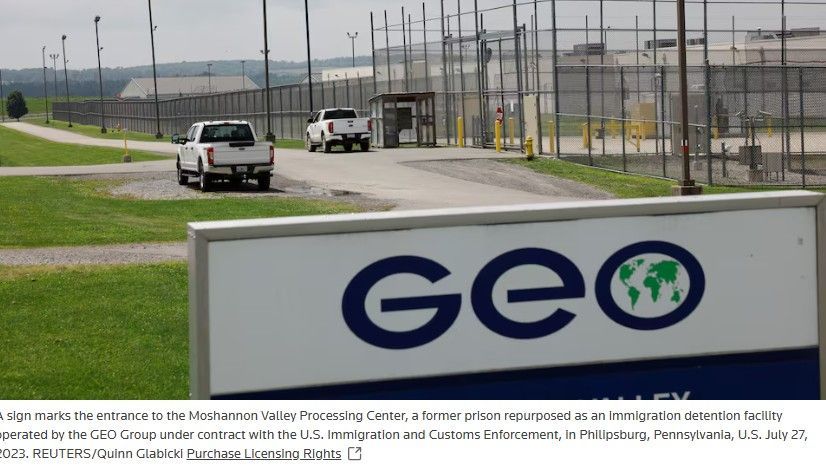
“As a PERS beneficiary, I am horrified that my pension funds private prison contractors and ICE detention centers.” Three recent Letters to the Editor of The Oregonian voice deep disquiet that the Treasury invests in immigrant detention facilities and spyware that are internationally recognized as engaging in human rights abuses and are flagrantly violating constitutional rights – instead of constructive investments. In June 2025, Oregon Treasury data shows investment of $51 million in CoreCivic and Geo Group, private prison contractors, and Palantir, maker of surveillance software used by ICE against US residents. Divest Oregon has been asking the Treasurer for years : Why aren’t investments screened to comply with Oregon Investment Council standards? See the blog: Why is the Treasury still investing workers’ retirement in fossil fuels, ICE contractors, and surveillance technology? for the backstory. In May, Treasurer Steiner stated that Treasury used its shareholder power to vote against four candidates for Geo Group’s board of directors because it was not conforming to Treasury’s investment standards – but kept the stock: Treasurer Steiner is “ deeply troubled ” about ICE contractor Geo Group…but OST has been a shareholder for years. The Treasury is investing public employee money. It has a responsibility to the beneficiaries and to all of us to follow its own investment guidelines. The letters voice a strong call for change: PERS should divest from ICE-contract prisons ( PDF , The Oregonian 7/27/2026) “Human Rights Watch reports that 52 people died in the custody of U.S. Immigration and Customs Enforcement in the first 500 days of President Donald Trump’s second term…." “It is tempting to feel powerless about this senseless waste of life. But here in Oregon, we have an opportunity to make a difference. We can demand that the Oregon Public Employees Retirement System divest from The Geo Group and Core Civic, two of the largest for-profit private prison corporations, which contract with ICE to run immigration detention facilities.” Oregon shouldn’t invest in ICE prisons ( PDF , The Oregonian 7/31/2026) “As a PERS member, I am not comfortable profiting from other people’s misery, and I am confident that others feel the same." “Reduced public investments and increased public awareness could even make investments in Geo Group and CORE Civic less attractive. Oregon should lead opponents of the cruelty in this immigration crackdown, epitomized by these prisons." Divest PERS from ICE-contract prisons ( PDF , The Oregonian 8/3/2026) “As a PERS beneficiary, I am horrified that my pension funds private prison contractors and ICE detention centers." “Oregon State Treasurer Elizabeth Steiner said she was 'deeply troubled' by Geo Group’s practices, and that the Treasury had used its shareholder power to vote against four candidates for the company’s board. Has that vote had any noticeable effect? Will Geo Group change its business practices as a result? These companies might take notice if the Oregon Treasury began pulling its investments.” “Like the people of Minneapolis, Oregon Gov. Tina Kotek, Oregon Attorney General Dan Rayfield and Portland Mayor Keith Wilson stood up to ICE. This is the moment for our Treasury staff to show the same courage."
July 6, 2026
Photo by SpaceX on Unsplash In a July 1 article Reuters reported that Oregon Treasurer Steiner wanted guidance from the federal Securities and Exchange Commission (SEC) about SpaceX. How should pension funds handle the new company with the giant market valuation? SEC Commissioner Mark Uyeda answered Elizabeth Steiner in an interview in Reuters . One takeaway is his simple point that if you don't like the governance arrangements of a stock, don't buy it. A message from the SEC's Uyeda: If you don't like SpaceX's governance, don't buy the shares ( Reuters Sustainable Finance , July 1, 2026) Note: The Oregon State Treasury has $6.8 million in exposure to SpaceX through one public equity index fund and one global equity portfolio ( Portland Business Journal July 2, 2026). Divest Oregon has made the same point to Treasurer Steiner, repeatedly. For example, Treasurer Steiner posted on Facebook on May 6, 2026 that she is “deeply troubled” by the ways ICE contractor Geo Group fails to adhere to Oregon Investment Council (OIC) policy. Divest Oregon responded : The Oregon Treasury has held stock in private prison/immigrant detention contractors for years, in spite of well-publicized abuse. If a company is violating OIC policy the Treasury has an obligation to sell the stock. In fact, Treasury’s screening process can and should prevent purchasing or holding stock that violates OIC/Treasury standards. The SEC Commissioner quoted in the Reuters ’ interview about SpaceX also says pension funds have the duty and ability to do such screening: Question by Reuters to SEC Commissioner Uyeda: "You write that ‘If prospective investors have concerns with the governance arrangements, then their most powerful tool is to not purchase shares of the stock.’ But critics like some big pension funds say the fast-track addition of SpaceX to big indexes could make them unwilling buyers of the stock. What would you say to such critics? Response from SEC Commissioner Uyeda: "Large pension funds have choices with respect to ​their investment decisions as part of their fiduciary duty to the plan. While index funds may have certain conveniences and low costs, there is a trade-off to outsourcing securities selection to a third party. There are alternatives, such as selecting a fund that follows a different index or is actively managed, or engaging in customized direct indexing that would provide more control over the portfolio.”
May 19, 2026
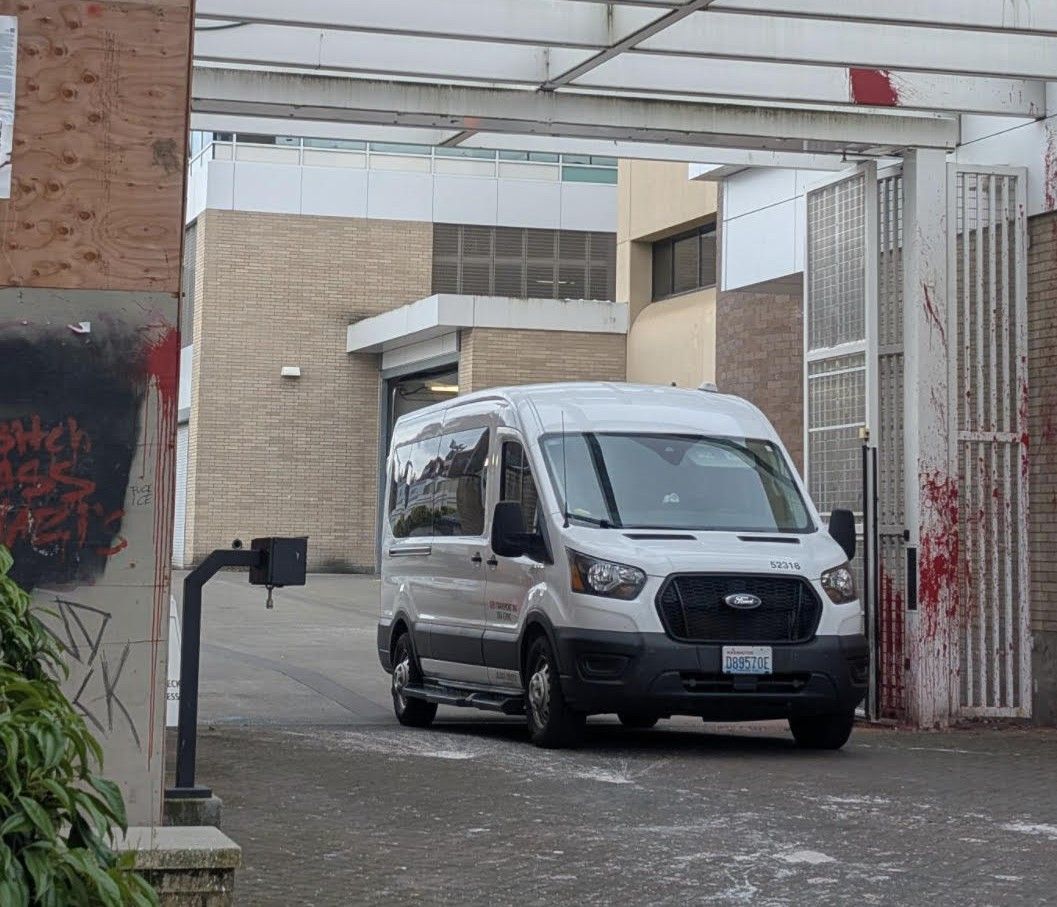
A Geo Group van leaving the Northwest ICE Processing Center in Portland Oregon. May 2026
April 9, 2026
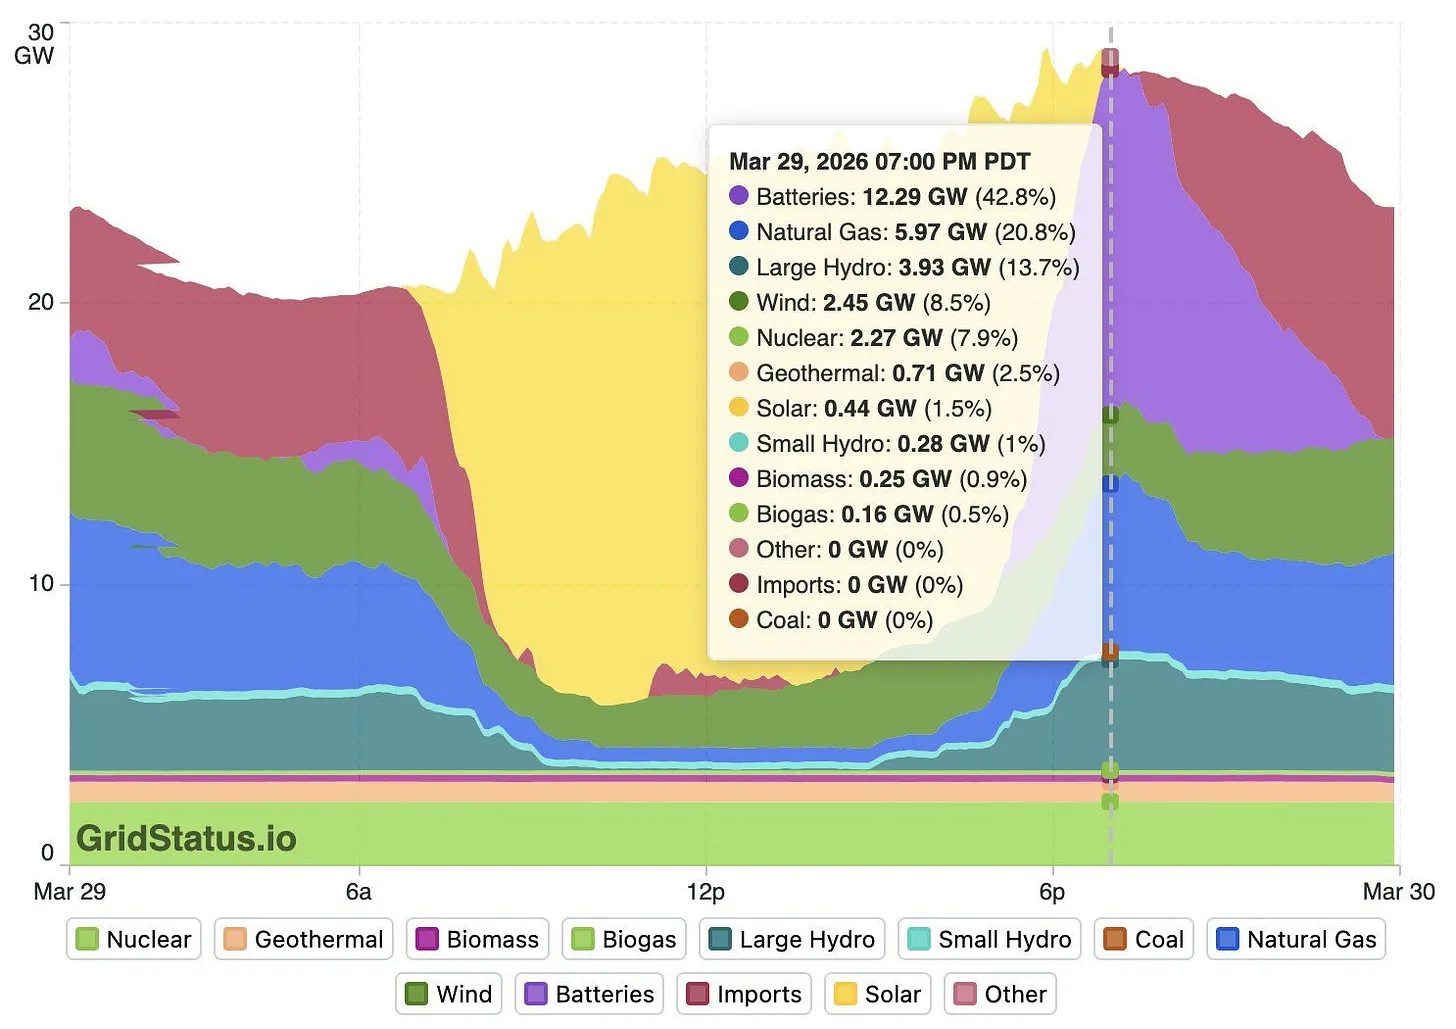
At the March 2026 OIC meeting, John Goldstein from Goldman Sachs spoke of the strength of renewable energy stocks (recap in Net Zero Investor 5/3/2026 ). Bill McKibben shows us how the sector is evolving with battery technology advances. Night into Day ( The Crucial Years substack 3/30/2026): “For the first time, the United States now has the capacity to supply 100% of domestic energy storage project demand with American-built systems,” said Noah Roberts, executive director of the U.S. Energy Storage Coalition. “That is a fundamental shift from where we were just a year and a half ago, when the majority of battery storage systems were imported.” “Already, the U.S. has enough capacity to meet demand for finished grid battery enclosures…. By the end of this year, the U.S. will also achieve self-sufficiency in a higher-value part of the supply chain: the battery cells themselves. It’s a major industrial coup that is bringing thousands of high-tech manufacturing jobs to communities across the country.” Solid-state batteries are becoming a possibility; they promise to solve several problems: “Batteries are now being tested by multiple companies that can go 800 miles on a single charge….“In September, Mercedes drove a modified EQS over 1,200 km (745 miles) using 106 Ah solid-state battery cells supplied by US-based Factorial Energy. Factorial launched the first commercial solid-state battery program in the US …earlier this year.” The Finnish company Donut Labs shows where this is heading: “The Donut batt can charge to full in five minutes…; has a practically unlimited lifespan (100,000 charging cycles); is unaffected by heat and cold (-30C to 100C); and contains no rare earth, precious metals or flammable liquid electrolytes. With all that, Donut Lab says it will be cheaper to produce than conventional lithium-ion batteries…” “And the technological miracles are only beginning. For instance, Christopher Mims reported last week in the Journal on a new round of ‘thermal batteries that store solar power as heat instead of electricity, perfect for use in high-temperature industrial processes.’” “Marija Maisch was reporting in January that…salt-based batteries are nearing price and performance parity, if not for cars then for utility scale batteries.” And this chart shows the surge of batteries coming online as solar installations lose sunlight. Night into day.
March 17, 2026
A question from Divest Oregon, a coalition of a hundred organizations with strong PERS representation, remains unanswered: What screening process does the Oregon State Treasury (OST) use, if any, when investing PERS funds or choosing investment managers? Is the Treasury screening investments in fossil fuel companies? Andrew Bogrand, Divest Oregon’s Communications Director, spoke at the Oregon Investment Council (OIC) in January 2026. He noted that investment in fossil fuels contributes to global instability, using Venezuela as an example. (See this blog .) The current Iran war emphasizes this point. Andrew regularly comments on the ties between insecurity and fossil fuels as a policy lead for human rights and natural resource justice at Oxfam. The argument that fossil fuel investments are a sensible diversification of a portfolio has long been outdated. But looking at the most recently published June 2025 public equity and fixed income data, the Treasury is still investing in fossil fuels. Under fiduciary duty and the Climate Resilience Investment Act ( CRIA ), the Treasury must move to alternative investments that align with the reality of climate change and a rapidly destabilizing world. Is the Treasury screening investments prone to legal liability, human rights abuses, or reputational risk? In an April 2023 report , Divest Oregon called out the Treasury's investment in private prisons and surveillance technology as context for the question: Does the Treasury have a screening process? If so, what is the screening process? One example given in that report was the NSO/spyware technology that OST heavily invested in. The Guardian reported extensively (2022) on the OST’s investment in NSO/Pegasus spyware: “However, it now appears that the Oregon pension fund, one of the most prominent in the US, gave its tacit approval over an investment in NSO several years ago – at a time when security researchers were already publicly raising alarms about the company.” In a more recent report, Oregon Treasury’s Investment Screening Failures ( October 2025 ), Divest Oregon again questioned the Treasury’s investment screening process. Examples of questionable investments included GEO Group, CoreCivic, and Palantir. Investments in GEO Group and CoreCivic fund private prison contractors and ICE detention centers. Investment in Palantir funds ICE surveillance software used against US residents. See additional information below for each of these companies. The most recent public data ( June 2025 ) shows that the Treasury continues to invest in these private prison and surveillance technology companies with a long history of human rights abuses and legal vulnerability. These companies are central to the current federal administration’s construction of a police state and its massive violation of due process. See Trump’s Mass Deportation Campaign ( The New Yorker 3/15/2026). For example: Recent private prison contractor GEO Group news: In February 2026, the Supreme Court found that GEO Group, a private prison operator running an Immigration and Customs Enforcement (ICE) facility, cannot claim governmental immunity from lawsuits for violating human trafficking laws, even if those violations were under government orders. Recent surveillance technology company Palantir news: In Portland, now, Palantir’s Elite app is being used to identify potential deportation targets, generate dossiers on individuals and provide a “confidence score” on the person’s address. ( The Guardian 3/13/2026) Why should the Treasury screen its investments? Screening is necessary to avoid investments that contravene Treasury standards, OIC policy, legal standards including fiduciary duty, or Oregon State law. For instance: The Oregon Department of Justice has recently opened an inquiry as to whether OST investment in companies with contractual ties to ICE violates the Oregon Sanctuary Promise Act of 2021 . The CRIA Act of 2025 mandates that the Treasury: -- “actively analyze and manage” climate risk to the portfolio -- report on its progress toward investing in public equity holdings that incorporate the tenets of a just transition in their overall priorities and portfolio
February 18, 2026
Part 2: Building on Oregon State Treasury’s 2025 Progress toward Net Zero Emissions Divest Oregon applauds initial action, offers recommendations for future reporting, including the use of multiple metrics
February 18, 2026
Part 1: Building on Oregon State Treasury’s 2025 Progress toward Net Zero Emissions Divest Oregon applauds initial action, offers recommendations for future reporting, including the use of multiple metrics